Private Credit Under Pressure: Key Litigation and Dispute Risks in the UK
Its appeal is clear: borrowers gain access to flexible finance, while investors seek higher returns in exchange for greater risk. However, the International Monetary Fund (IMF) in its Global Financial Stability Report of April 2024 (the ‘April 2024 Report’), warned that private credit also brings greater opacity, exposure to riskier borrowers than traditional public credit markets and less transparent pricing. More recently it has been reported by the Financial Times that the number of defaults are increasing to levels not seen since 2017.
The private credit market has expanded significantly in the last 10 years, with an estimated USD 2.1 trillion of assets under management, from around an estimated half a trillion in 2015. It is also impossible to write about any sector without mentioning the impact of AI and the private credit market is no exception, with the Bank for International Settlements recently finding that a third of all private credit transactions relate to the AI boom in infrastructure spending. A notable structural feature of this growth has been the increasing use of special purpose vehicles (SPVs) to originate and warehouse exposures, particularly in financing AI-related infrastructure. These structures can manage risk, but they may also add layers of complexity and reduce transparency for investors assessing underlying asset quality and leverage.
For UK clients, the concern is no longer just credit risk, but extends to how quickly pressure in the private credit market could translate into disputes. That risk is becoming increasingly harder to ignore. Reflecting those concerns, in December 2025, the Bank of England launched its second system-wide exploratory scenario exercise focused on private markets, including private credit, to assess how stress in the sector could be transmitted more widely across the financial system
The issues recently emerging around Market Financial Solutions Limited (MFS) offer a practical example of how stress in this market can translate into legal and regulatory scrutiny. On 20 March 2026, the Financial Conduct Authority (FCA) confirmed that it had opened an enforcement investigation into MFS following the firm’s entry into administration in February 2026. The FCA also made clear that MFS was an Annex 1 business, meaning it was supervised for anti-money laundering purposes only and was not subject to the FCA’s wider conduct regime. That distinction is significant: where lending falls outside the regulated perimeter, customers may also be unable to refer complaints to the Financial Ombudsman Service, making court proceedings more likely.
What are the key litigation risks in private credit?
First, security and enforcement disputes. Where collateral has been overstated, imperfectly documented or pledged more than once, lenders can quickly find themselves in priority disputes and contested enforcement proceedings. Public reporting around MFS has highlighted allegations of collateral shortfalls and “double pledged” loans, illustrating the kind of issues that can give rise to urgent court actions and complex multi-party claims.
Security and enforcement disputes
Second, misrepresentation, investor and professional negligence claims. In a stressed market, investors are likely to scrutinise whether the underlying risks, liquidity profile and asset quality were properly explained at the outset. That is particularly significant in private credit, where valuations are inherently less transparent and losses may crystallise more slowly than in public markets; the IMF in its April 2024 Report has identified opacity and delayed loss recognition as structural vulnerabilities in the sector. Once losses begin to emerge, scrutiny is also likely to extend beyond the borrower or originator to the wider transaction chain, with lawyers, administrators and valuers potentially coming under examination for their role in the structuring, diligence and ongoing monitoring of the deal.
Misrepresentation, investor and professional negligence claims
Third, insolvency-related litigation. Once a fund vehicle, lender or borrower enters distress, office-holders, administrators/liquidators and creditors are likely to scrutinise related-party dealings, adequacy of the security package and historic asset movements in close detail. In the UK, that scrutiny can quickly develop into claims for misfeasance, transactions at an undervalue, preferences, as well as applications for tracing and freezing relief. The reporting around MFS is a reminder of how rapidly matters can escalate where asset preservation and recovery become the immediate priority.
Insolvency-related litigation
Fourth, waiver and no‑oral modification clauses (“NOM” clauses). In practice, lenders in the private credit market may tolerate shortfalls or accept reduced payments without formally reserving their rights. That flexibility can come at a cost: borrowers may later contend that the lender has waived strict compliance or agreed to a contractual variation. While NOM clauses are designed to guard against informal amendments, they do not eliminate the risk of fact-sensitive disputes where the parties’ conduct departs from the written terms. In an enforcement scenario, such arguments can materially complicate or even undermine a lender’s position.
Waiver and no-oral modification clauses
For clients, the practical message is straightforward: now is the time to test whether valuation processes are both independent and properly documented, whether security packages are robust and whether disclosures to investors and counterparties accurately reflect the underlying risks. This approach is consistent with the FCA’s recent review of private market valuation practices, which identified conflicts, transparency and governance as key areas of focus in private credit.
Private credit will continue to play an important role in the UK financing landscape. However, as the market matures and pressure begins to build, disputes are likely to become an increasingly visible feature of the sector, particularly if the use of special purpose vehicles to finance AI infrastructure continues to expand. For clients, the key question is no longer simply where signs of stress may emerge, but how quickly that stress may crystallise into claims.
If you would like to discuss any of the issues raised in this article or require advice in relation to a private credit dispute, please contact a member of our Dispute Resolution team.
“I was working as a waitress in a cocktail bar”
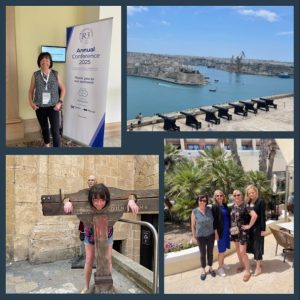
Karen Dobson, Partner in Dispute Resolution and Corporate Recovery & Insolvency at Sherrards, recently attended the highly anticipated R3 2025 Annual Conference, held this May in Malta.
This year’s conference centred on the theme “Embracing Change: Shaping the Profession to be Fit for the Future”, highlighting the evolving landscape of the insolvency profession.
The event explored key issues such as attracting and nurturing the next generation of professionals, leveraging emerging technologies—including artificial intelligence—and responding to shifting workplace expectations across generational divides.
Karen described the conference as “truly excellent,” praising not only the quality of the venue, speakers, and delegates, but also the opportunity to engage in valuable networking in a stunning setting with great weather.
It was lovely to hear presentations by younger professionals in the industry, who spoke extremely well and many of whom shared inspiring personal stories of their unconventional routes into the industry one of whom starting off working as a waitress in a cocktail bar where she met a customer who influenced her into becoming a lawyer.
The keynote speaker, Dr Paul Redmond, a renowned expert on generational trends in the workplace, delivered a standout session that combined humour and insight. His talk struck a particular chord with attendees, including Karen, who found herself playfully teased by colleagues for her ‘baby boomer’ credentials—culminating in a light-hearted photo of her in the stocks, ostensibly for one-finger texting!
Throughout the conference, Karen strengthened her close ties with her long-time industry peers as well as reconnecting with familiar faces and she relished the opportunity to network with many key figures across the profession.
Karen’s participation in the R3 Annual Conference exemplifies Sherrards’ ongoing commitment to industry engagement, future-facing dialogue, and client-focused development in the ever-evolving insolvency landscape.
For more information about Sherrards’ insolvency offering, speak to Karen Dobson on +44 (0) 1727 832 830 or kd@sherrards.com.